Managing personal finances effectively is one of the most important skills you can develop for a secure and stress-free future. Whether you are earning your first salary, running a small business, supporting a family, or preparing for retirement, knowing how to manage your money can help you make better financial decisions.
Many people struggle with money not because they earn too little, but because they do not have a clear financial plan. Without tracking income and expenses, it is easy to overspend, accumulate debt, and miss opportunities to save or invest.
The good news is that improving your finances does not require complicated strategies. With a simple budget, clear financial goals, controlled spending, emergency savings, and consistent habits, you can take control of your money.
In this guide, we will explore practical ways to manage personal finances better, reduce financial stress, save more money, and build a stronger financial future.
What Does Managing Personal Finances Mean?
Personal finance management means making informed decisions about how you earn, spend, save, borrow, and invest your money.
It involves several important areas, including:
- Managing monthly income
- Creating and following a budget
- Controlling unnecessary expenses
- Building an emergency fund
- Paying off debt
- Saving for short-term and long-term goals
- Investing wisely
- Planning for major purchases
- Preparing for retirement
Good financial management is not about avoiding every purchase or living an extremely restrictive lifestyle. Instead, it is about making sure your money is being used according to your priorities.
1. Understand Your Current Financial Situation
Before changing your financial habits, you need to understand where your money currently goes.
Start by writing down all sources of income. This may include your salary, freelance income, business earnings, rental income, or other regular payments.
Next, list your monthly expenses.
Separate them into categories such as:
- Rent or mortgage
- Utilities
- Groceries
- Transportation
- Insurance
- Education
- Entertainment
- Shopping
- Debt payments
- Subscriptions
- Savings
Review your bank statements and payment records if necessary. This can reveal expenses you may have forgotten about.
Once you know your income and expenses, calculate your monthly cash flow.
Monthly income − monthly expenses = money available for saving, investing, or additional debt payments.
This simple calculation gives you a starting point for improving your financial situation.
2. Create a Realistic Monthly Budget
A budget is one of the most useful tools for managing personal finances better.
A budget gives every part of your income a purpose. Instead of spending money and wondering where it went at the end of the month, you decide in advance how much you can afford to spend.
A simple budget might include:
- Essential expenses
- Savings
- Debt payments
- Personal spending
- Investments
One popular approach is the 50/30/20 budgeting method. Under this framework, approximately 50% of income is allocated to needs, 30% to wants, and 20% to savings or debt repayment.
However, these percentages are not strict rules. Your situation may require a different balance.
For example, someone living in an expensive city may spend more than 50% on essential expenses. Someone aggressively paying off debt may dedicate more than 20% to debt repayment.
The best budget is one that is realistic enough for you to follow consistently.
3. Track Your Spending
Creating a budget is only useful if you monitor your actual spending.
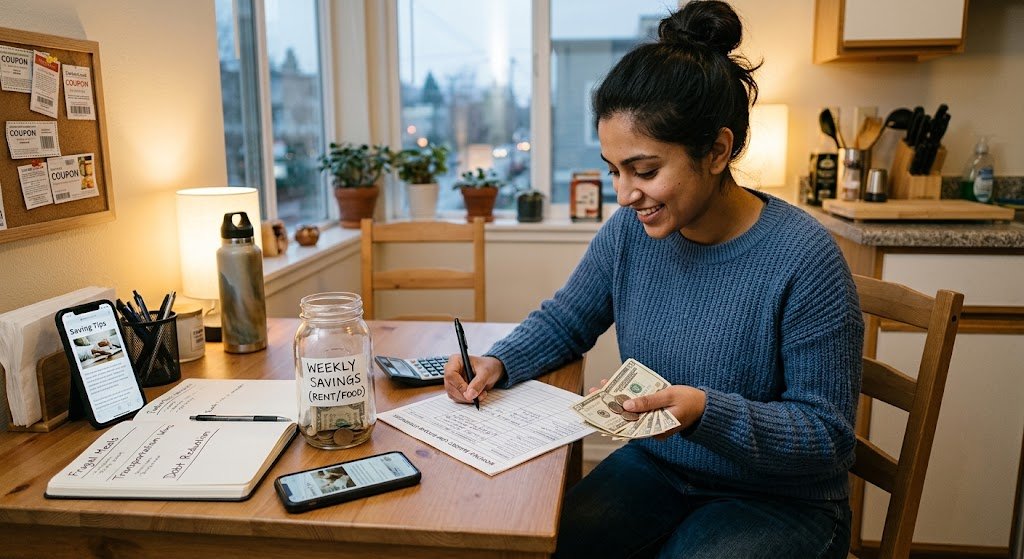
Track every purchase for at least one month. You can use:
- A spreadsheet
- A budgeting app
- A notebook
- Your bank’s transaction history
At the end of the month, compare your actual expenses with your budget.
You may discover that small purchases are taking a significant amount of your income. Daily snacks, food delivery, subscriptions, online shopping, and frequent entertainment expenses can add up quickly.
Tracking spending helps you identify patterns and make informed decisions.
4. Separate Needs From Wants
One of the easiest ways to improve your finances is to distinguish between things you need and things you simply want.
Needs are expenses required for basic living, such as:
- Housing
- Food
- Utilities
- Basic transportation
- Essential healthcare
Wants can include:
- Expensive restaurants
- New gadgets
- Designer clothing
- Entertainment
- Unnecessary subscriptions
This does not mean you should eliminate all wants. Enjoying your money is part of a healthy financial life.
The goal is to make sure your wants do not prevent you from paying bills, saving money, or reaching important financial goals.
5. Build an Emergency Fund
Unexpected expenses can seriously damage your finances if you have no savings.
A car repair, medical bill, job loss, home repair, or family emergency can require money that you did not plan to spend.
An emergency fund provides a financial safety net.
Start by setting a small initial target. Once you develop the habit of saving, gradually work toward having several months of essential expenses available.
Keep emergency savings somewhere accessible and separate from your everyday spending money.
The purpose of an emergency fund is not to generate maximum investment returns. Its primary purpose is to provide financial protection when something unexpected happens.
6. Reduce Unnecessary Expenses
You do not always need to earn more money to improve your financial situation. Sometimes reducing unnecessary expenses can make a major difference.
Review recurring expenses and ask yourself:
“Do I really use this?”
Look at:
- Streaming subscriptions
- Gym memberships
- Mobile plans
- Software subscriptions
- Food delivery
- Frequent shopping
- Unused memberships
Cancel services you rarely use.
You can also reduce costs by comparing prices before making large purchases, buying during sales, preparing meals at home, and avoiding impulse purchases.
Small savings become meaningful when you repeat them every month.
7. Avoid Impulse Buying
Impulse purchases can make it difficult to maintain a budget.
Before buying something that was not planned, give yourself time to think about it.
For larger purchases, consider using a 24-hour or 48-hour waiting period. If you still want the item after thinking about it and it fits your budget, you can make a more informed decision.
Another useful technique is to remove saved payment information from shopping websites. Adding an extra step between wanting something and purchasing it can reduce unnecessary spending.
8. Pay Down High-Interest Debt
Debt can make it difficult to build wealth because interest consumes part of your income.
Credit cards and other high-interest debts deserve particular attention.
Start by listing your debts, including:
- Total balance
- Interest rate
- Minimum payment
- Due date
Then create a repayment strategy.
Two popular methods are the debt avalanche and debt snowball.
With the debt avalanche method, you focus on paying the highest-interest debt first while maintaining minimum payments on other debts.
With the debt snowball method, you focus on paying off the smallest balance first to create psychological momentum.
Choose the method you are most likely to follow consistently.
9. Automate Your Savings
Saving money becomes easier when you do not have to remember to do it manually every month.
Consider setting up an automatic transfer from your main account to a dedicated savings account shortly after receiving your income.
Even a small amount can help you develop the habit.
For example, if you automatically save $100 each month, you would accumulate $1,200 over a year before considering any interest or investment returns.
The exact amount is less important than creating a consistent habit that fits your financial situation.
10. Set Specific Financial Goals
Vague goals such as “I want to save more money” are difficult to measure.
Instead, create specific goals.
For example:
- Save $1,000 for emergencies
- Pay off a credit card within 12 months
- Save for a house deposit
- Build a travel fund
- Invest a certain amount every month
- Save for education
- Prepare for retirement
Give each goal a target amount and deadline.
Breaking a large goal into smaller monthly targets makes it easier to monitor your progress.
11. Learn the Basics of Investing
Once your basic financial foundation is strong, you can learn about investing.
Investing can potentially help your money grow over the long term, but all investments involve some level of risk.
Before investing, understand concepts such as:
- Risk and return
- Diversification
- Compound growth
- Investment fees
- Time horizon
- Asset allocation
Do not invest money that you may need immediately for rent, bills, or emergencies.
Avoid making investment decisions simply because something is trending on social media. Research investments carefully and understand what you are buying.
If necessary, consider speaking with a qualified financial professional.
12. Protect Yourself From Financial Emergencies
Good personal finance management also includes protection.
Depending on your circumstances, you may need appropriate insurance coverage for areas such as health, property, vehicles, or income protection.
You should also maintain important financial documents securely and review your accounts regularly.
Be careful with online financial scams. Never provide passwords, one-time verification codes, or sensitive banking information to unknown individuals.
Financial security involves protecting both your money and your personal information.
13. Be Careful With Lifestyle Inflation
Lifestyle inflation happens when spending increases as income increases.
For example, someone might receive a salary increase and immediately move to a more expensive apartment, buy a more expensive car, and increase entertainment spending.
Although enjoying higher income is reasonable, increasing expenses too quickly can prevent you from becoming financially stronger.
When your income rises, consider directing part of the increase toward:
- Savings
- Investments
- Debt repayment
- Emergency funds
- Long-term goals
You can still improve your lifestyle while making sure your financial progress continues.
14. Review Your Finances Every Month
Financial management should become a regular habit rather than a one-time activity.
Set aside some time each month to review:
- Income
- Expenses
- Savings
- Debt
- Investments
- Financial goals
Ask yourself:
What went well this month?
Where did I overspend?
What can I improve next month?
Regular reviews help you identify problems before they become serious.
15. Increase Your Income When Possible
Reducing expenses is useful, but increasing income can also accelerate financial progress.
Depending on your skills and circumstances, you could explore:
- Freelancing
- Part-time work
- Online services
- Selling products
- Consulting
- Learning new professional skills
- Starting a small business
The goal is not necessarily to work constantly. Instead, focus on developing valuable skills that can increase your earning potential over time.
When additional income becomes available, avoid immediately increasing your lifestyle expenses.
Common Personal Finance Mistakes to Avoid
Even financially responsible people can make mistakes. Some common problems include:
Not Having a Budget
Without a budget, it can be difficult to know whether your spending matches your priorities.
Ignoring Small Expenses
Small recurring expenses can become significant over time.
Using Credit for Everything
Credit can be useful, but relying heavily on borrowed money can create long-term financial pressure.
Having No Emergency Savings
Unexpected expenses are inevitable. Having savings can reduce the need to borrow money during emergencies.
Chasing Quick Investment Profits
Promises of guaranteed high returns are often a warning sign. Always research investments before committing your money.
Comparing Your Lifestyle With Others
Social media can create unrealistic expectations about wealth and spending. Focus on your own financial goals instead.
A Simple Personal Finance Routine
If you want a simple system, try this monthly routine:
Step 1: Calculate your total income.
Step 2: Review all expenses.
Step 3: Pay essential bills.
Step 4: Transfer money to savings.
Step 5: Make planned debt payments.
Step 6: Invest according to your financial plan.
Step 7: Review unnecessary spending.
Step 8: Check progress toward your goals.
Step 9: Adjust next month’s budget.
This process can take less than an hour once you become familiar with it.
Final Thoughts
Learning how to manage personal finances better is not about becoming perfect with money. It is about developing consistent habits that help you make better decisions.
Start by understanding your income and expenses. Create a realistic budget, track your spending, reduce unnecessary costs, build an emergency fund, and work toward paying down expensive debt.
As your financial foundation becomes stronger, focus on long-term goals such as investing, retirement planning, and increasing your income.
The most important step is simply to begin. You do not need a large salary or complicated financial strategy to improve your money habits. Small, consistent improvements can make a meaningful difference over time.
Remember that personal finance is personal. The right strategy depends on your income, expenses, goals, responsibilities, and risk tolerance. Build a plan that fits your situation and review it regularly as your circumstances change.
Start with one financial improvement today. Track one expense, save a small amount, cancel one unnecessary subscription, or create your first budget. Over time, these small actions can become the foundation of a much stronger financial future.